

Carbon Trading Systems and the Reshaping of the Construction Industry’s Future
Share:
The construction industry is one of the largest sources of greenhouse gas emissions, accounting for around 37% of total global CO₂ emissions (IEA, 2022). The expansion of Emissions Trading Systems (ETS) beyond the energy sector into carbon-intensive industries — including building materials and operational processes — is reshaping the entire cost structure and competitive strategies of the construction sector.
1. Introduction
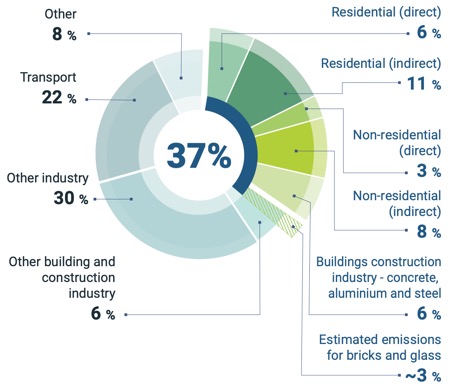
The construction industry is one of the largest sources of greenhouse gas emissions, accounting for around 37% of total global CO₂ emissions (IEA, 2022). The expansion of Emissions Trading Systems (ETS) beyond the energy sector into carbon-intensive industries — including building materials and operational processes — is reshaping the entire cost structure and competitive strategies of the construction sector.
2. ETS and the Cost of Carbon
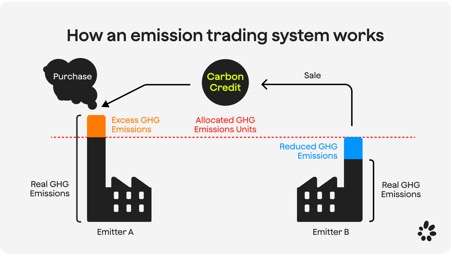
ETS establishes an emission cap and allocates allowances to companies. Those exceeding their quota must purchase additional credits, while those reducing emissions can sell their surplus.
This mechanism turns carbon into an economic cost and a tradable asset.
In the construction sector, this means that both embodied carbon (emissions embedded in materials) and operational carbon (emissions during building use) will directly influence pricing structures.
3. Impact on Building Materials
High-emission materials such as cement, steel, and glass will face significant cost pressures.
A recent study published in the Journal of Cleaner Production found that ETS implementation significantly increases the cost of carbon-intensive materials, forcing the construction sector to shift toward products with transparent Environmental Product Declarations (EPD) and lower Life Cycle Assessments (LCA).
4. Technological Innovation and Carbon Management
ETS serves as a major driver of technological innovation.
Research by ICAP (2018) demonstrates a strong correlation between ETS adoption and the rise in low-carbon technology patents.
In the construction context, this is reflected through accelerated investment in low-clinker cement, electric arc furnace (EAF) steel, material recycling, and resource-efficient design.
5. Data Transparency and MRV Systems
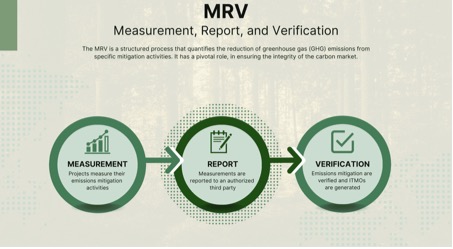
To participate in ETS, companies must implement Measurement, Reporting, and Verification (MRV) systems.
This structure closely aligns with existing green building certifications (LEED, BREEAM, LOTUS) and EPD frameworks.
Enterprises that have already adopted such systems will streamline ETS compliance while enhancing data transparency.
A study published by Springer (Li et al., 2023) emphasizes MRV as a foundational pillar for building carbon trading systems within the construction industry.
6. Linkage with Green Finance
International financial institutions such as IFC, ADB, and AIIB increasingly tie funding eligibility to emission transparency.
Thus, carbon transparency is not only a regulatory requirement under ETS but also a prerequisite for accessing green capital.
This trend strengthens the connection between carbon governance and financial competitiveness in the construction sector.
7. Outlook for Vietnam
Vietnam has begun the pilot phase of its domestic carbon market in 2025, with full operation expected by 2028 (Reuters, 2025).
The steel and cement industries will be the first to be affected, but the impacts will inevitably extend across the entire construction value chain — particularly as the EU’s Carbon Border Adjustment Mechanism (CBAM) applies to Vietnamese exports.
8. Conclusion
ETS is redefining how the construction industry operates: shifting from a cost model driven primarily by materials and labor to one shaped by carbon costs, transparent data, and low-carbon technologies.
Enterprises that proactively adopt LCA, EPD, and green certifications before ETS becomes mandatory will secure a sustainable competitive advantage — both in market positioning and financial access.
Latest news

GRI standards now available in Vietnamese: What it means for ESG Reporting in Vietnam
On 14 September 2026, the Global Reporting Initiative (GRI) announced that the latest versions of its complete sustainability reporting Standards are now available in Vietnamese. The release covers the revised Universal Standards, all current Sector Standards and the latest Topic Standards, including GRI 101: Biodiversity 2024, GRI 102: Climate Change 2025 and GRI 103: Energy 2025. [1] GRI first made its Standards available in Vietnamese in 2017. The 2026 update brings Vietnamese-language users up to date with the current modular system and gives companies across the country direct access to the same reporting framework used internationally to identify, manage and disclose impacts on the economy, environment and people. [1] GRI is also expanding engagement in Vietnam through training, technical guidance and knowledge-sharing, with particular attention to small and medium-sized enterprises (SMEs). According to GRI, these programs are intended to help organizations assess sector-specific impacts, strengthen value-chain resilience and respond to disclosure expectations from international markets and sustainable finance providers. [1]

Green Finance in Vietnam: Buildings Seeking Capital Must Start with Data
On 18 September 2026, the Vietnam International Financial Centre in Da Nang (VIFC-DN) identified green finance and the carbon market as priority areas for development. The announcement was not accompanied by a specific lending product, but it sent a clear signal about the direction of green capital in the years ahead: projects will increasingly need to demonstrate environmental performance through data that can be measured, reviewed and independently verified. For developers, industrial asset owners, FDI companies and building operators, the key question is no longer simply “Is this building green?” The more important questions are: “What data proves that it is green, who verifies that data, and will the data continue to be maintained after financing has been disbursed?”

Green industrial parks: A key factor in attracting the next generation of FDI
As international investment increasingly prioritises sustainable development, green industrial parks are emerging as a new competitive benchmark for the market. The attractiveness of an industrial park is no longer determined solely by land availability or rental rates. Today, competitiveness depends increasingly on infrastructure quality, operational capability, ESG performance and the ability to create an efficient and sustainable production ecosystem for investors.


Circular economy under scarcity pressure: Is resource autonomy the solution?
Amid increasing resource scarcity and escalating geopolitical instability, the concept of resource autonomy is emerging as a strategic priority. This article examines how resource autonomy not only complements—but may even surpass—the circular economy as a framework for enabling industrial systems to adapt to the future.

Advancing Green Building Materials for Sustainable Development
As pressure to reduce carbon emissions continues to intensify, green building materials are becoming an increasingly important direction for Vietnam’s construction industry. Green material solutions can help improve energy efficiency, reduce operating costs and minimise environmental impacts. At the same time, the use of environmentally responsible materials can support projects seeking green building certifications such as LEED, LOTUS and EDGE. For businesses, this is becoming an important factor in strengthening competitiveness and supporting long-term sustainable growth.
Build Green, Build with ARDOR Green

